The strongest current coffee market trends are the spread of specialty-style drinks, growth in cold and ready-to-drink formats, and attempts to bring café-style coffee into the home. As of November 2026, the evidence supports these longer-term changes more clearly than claims that any single fashionable drink is taking over, while supply uncertainty and traceability requirements continue to shape the business.
In short
- Keep the geography attached: US consumption surveys are useful indicators, not measurements of UK habits.
- Separate cold coffee from nitro: the former is a broad category; nitrogen-infused coffee is one smaller part.
- Convenience and quality can overlap: ready-to-drink products and concentrates offer different routes to café-style drinks.
- Check what “growth” measures: rising sales value does not necessarily mean more coffee consumed.
- Ask for evidence behind sustainability claims: certification, farm traceability, packaging and disposal are different questions.
Reading current coffee market trends
A useful market trend changes purchasing, consumption or business practice beyond a launch campaign. This article concentrates on those structural changes, using dated evidence rather than treating each new product as a prediction.
The evidence needs sorting before it needs celebrating. A consumer survey measures reported behaviour; a company announcement describes that company’s performance; trade statistics measure goods moving through supply chains. They cannot be substituted for one another.
For example, the National Coffee Association’s autumn 2026 US report used a nationally representative survey of 1,882 adults, conducted from 8 to 24 June 2026. Its publication season should not be mistaken for its fieldwork season, particularly when discussing iced drinks.
For the wider structure behind these shifts, start with our coffee industry guide.
Third-Wave Coffee Movement
Third-wave coffee treats coffee as a product with a distinctive origin and production history, rather than simply a standard hot drink. UC Davis Library’s account associates the movement with single-origin beans, information about farming and processing, lighter roasting, manual brewing and freshness transparency.
Its lasting contribution is the expectation that a seller should explain what makes a coffee different. Origin, processing and sensory characteristics become part of the buying decision.
“Third wave” and “specialty coffee” are related, but not interchangeable. The Specialty Coffee Association’s current definition recognises distinctive attributes and the additional value attached to them. Those attributes include flavour and texture, but also information such as origin, producer and growing practices.
What the data actually shows
In the NCA’s June 2026 US survey, 48% of adults reported drinking specialty coffee the previous day. That indicates broad participation in the survey’s specialty category, not that almost half the population bought independently assessed, traceable single-origin beans.
The NCA’s consumer definition includes espresso-based drinks, cold brew, nitro and other formats, alongside traditionally brewed coffee perceived as premium. It is therefore broader than the craft-focused meaning readers may associate with third-wave cafés.
The defensible conclusion is that specialty-style drinks have reached a wide audience in that market. To understand the businesses focused more specifically on provenance and roasting, read about specialty coffee roasters.
Rise of Nitro Coffee
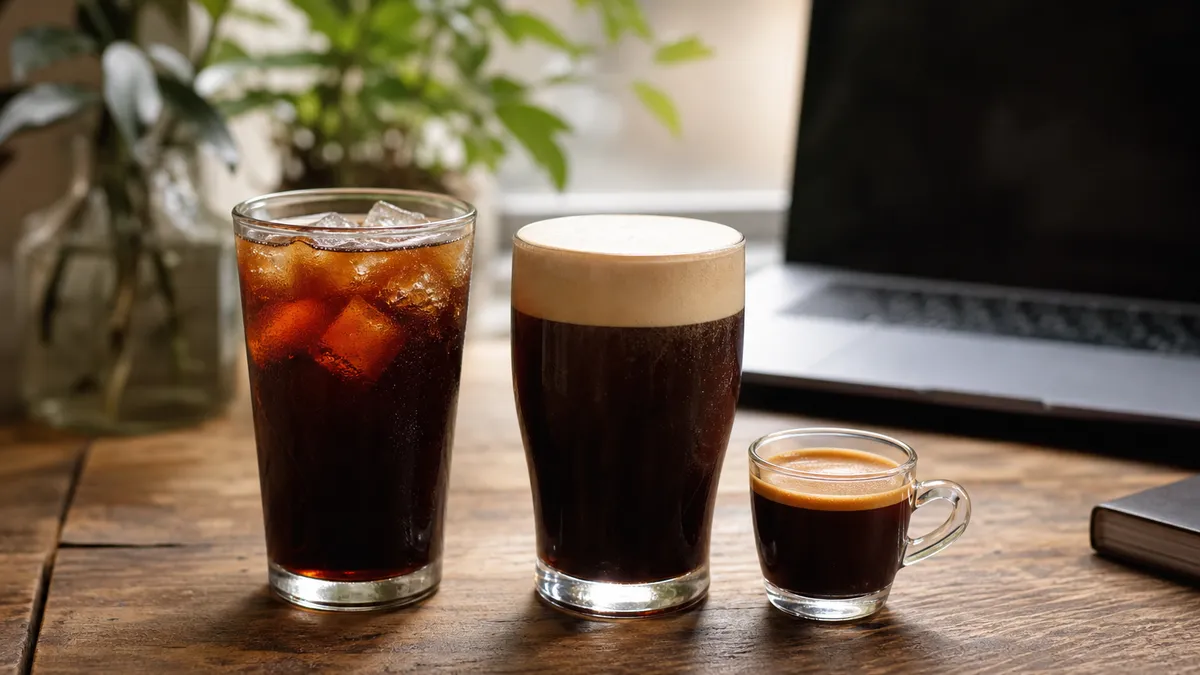
Nitro coffee is coffee infused with nitrogen. Starbucks describes its version as cold brew infused during dispensing, producing small bubbles, a cascading appearance and a creamy head.
That visual effect makes nitro conspicuous. It does not make nitro synonymous with the much larger cold-coffee category.
Three distinctions help:
- Iced coffee describes coffee served cold with ice, not necessarily a particular extraction method.
- Cold brew describes coffee extracted without hot brewing water.
- Nitro coffee describes nitrogen infusion, commonly applied to cold brew.
Cold coffee has the stronger structural signal
The NCA reported that 21% of past-day US coffee drinkers had consumed cold coffee in its June 2026 survey, compared with 16% in 2022. It also explicitly identified a summer increase, so a winter-to-summer comparison alone would overstate the evidence for lasting growth.
Its autumn 2026 media highlights provide a useful scale check: 21% of US adults reported cold brew consumption during the previous week, compared with 7% for nitro. These are participation figures, not shares of drinks sold.
Nitro therefore deserves attention as a distinct format, but the evidence here supports a smaller role than cold brew overall. Neither figure establishes UK demand.
For a workplace considering cold coffee, the practical lesson is to test the drink people want before choosing the dispensing equipment. A visible cascade is attractive; repeat orders are the more useful business signal.
Ready-to-drink coffee: convenience without brewing
Ready-to-drink, usually shortened to RTD, means coffee supplied as a finished beverage rather than something the customer must brew or dilute. It should not be confused with a concentrate intended for mixing.
The NCA’s autumn 2026 highlights recorded RTD among the preparation formats used by 17% of past-day US coffee drinkers. This measures reported use, not the category’s share of retail sales or coffee volume.
Company reporting supplies a second, narrower signal. In its results published on 22 October 2026, Nestlé attributed cold-coffee momentum in its Asia, Oceania and Africa division to RTD expansion, liquid concentrates and soluble iced-coffee offerings.
That is evidence of one manufacturer’s activity across a particular division, not an independent global market estimate. Nevertheless, it shows why cold coffee should be analysed across several formats rather than through café menus alone.
The structural development to watch is convenience taking different forms: a finished drink, a product mixed at home, or coffee prepared to order. Our guide to coffee industry giants explains the larger businesses behind such portfolios.
At-home premiumisation
At-home premiumisation means choosing a coffee experience perceived as better, more distinctive or closer to a café drink. It need not mean buying complicated equipment.
The Netherlands’ Centre for the Promotion of Imports from developing countries, CBI, identified premiumisation as a central feature of the UK market in its August 2026 assessment. It distinguished growth in value from growth in volume.
That distinction matters. Market value can increase without an equivalent increase in the amount of coffee consumed. Nor does a premium product launch establish how many households repeatedly buy it.
The NCA’s autumn 2026 highlights found that 83% of past-day US coffee drinkers had coffee at home. This establishes the importance of the home setting in that survey, but does not itself prove premiumisation.
Two questions are better than one
For this article, the useful distinction is between craft-led premiumisation, where the interest is provenance and preparation, and convenience-led premiumisation, where the aim is a particular drink with less preparation.
This is an analytical distinction, not an official market classification. It helps explain why a manual brewer and a coffee concentrate might serve similar aspirations without serving identical customers.
For UK readers, the sensible conclusion is that premiumisation is a documented market direction, while its precise at-home scale remains less clear in the public evidence reviewed here. See the UK coffee industry for national context.
Sustainability: from attractive claims to verifiable practice
Sustainability is not a single measurable trend. It includes farming practices, sourcing conditions, traceability, emissions, packaging and waste management.
CBI identifies Rainforest Alliance, Fairtrade and organic certification as established features of the UK coffee market. Their presence should prompt a more precise question: what does the particular certification or claim cover?
The Competition and Markets Authority’s Green Claims Code requires environmental claims to be clear, accurate and substantiated. A statement about recyclable packaging is not evidence that the coffee inside has a lower overall environmental impact.
Life-cycle assessment, which estimates impacts across specified stages of a product’s life, offers a more useful framework than judging the pack alone. Nab and Maslin’s peer-reviewed 2020 modelling of coffee supplied to the UK identified transport choices, agricultural inputs and water-heating efficiency among relevant factors. Its scenarios are not a universal footprint for every cup.
Traceability and disposal are becoming practical requirements
As checked in November 2026, EU guidance lists coffee within the deforestation regulation’s scope. The Council gives application dates of 30 December 2026 for operators other than micro and small operators, and 30 June 2027 for micro and small operators.
This is an EU-market requirement, not a blanket UK domestic rule. For businesses supplying that market, plot-level traceability is a concrete issue to watch.
In England, workplace recycling rules already require separate food-waste collection, including coffee grounds, subject to the temporary micro-firm exemption until 31 March 2027. DEFRA says compostable packaging must not go into that food-waste stream. These dates and instructions should not be applied to the other UK nations.
Prices and supply resilience
Coffee market trends also depend on the availability of green coffee, meaning unroasted beans. Consumer interest cannot be read separately from supply conditions.
The ICO’s September 2026 Coffee Market Report described stronger Brazilian availability alongside low certified arabica stocks and weather uncertainty. That combination illustrates why a favourable harvest signal does not remove every supply risk.
It also cautions against a simple story in which coffee prices move permanently in one direction. A monthly report is a dated assessment, not a reliable prediction of the next harvest or retail purchasing decision.
For the market mechanisms, rather than repeating them here, read coffee futures and the C-market.
When reviewing workplace supply, ask for itemised written quotations covering coffee, consumables, servicing, equipment arrangements and delivery. Compare the assumptions and contractual terms, not just the headline offer.
Trends to watch: a dated evidence checklist
The following is a monitoring framework, not a forecast. Its starting evidence was checked in November 2026.
| Direction | Dated evidence | What would strengthen the case? |
|---|---|---|
| Specialty-style drinks reaching broader audiences | NCA US consumer survey, June 2026 | Consistent repeat surveys and comparable UK research |
| Cold coffee extending its reach | NCA comparisons with 2022, published September 2026 | Same-season comparisons separating drink formats |
| Convenience-led coffee preparation | Nestlé divisional reporting, October 2026 | Independent repeat-purchase and volume evidence |
| UK premiumisation | CBI assessment, August 2026 | Household evidence separating product mix from inflation |
| More demanding traceability | EU implementation guidance checked November 2026 | Documented compliance and reliable farm-level records |
For a roaster, retailer or office buyer, the next step is modest: record what customers or colleagues actually choose, how frequently they choose it, and what remains unused. Keep that evidence separate from requests to try something once.
The most useful coffee market trends are those that survive this test: repeated behaviour, comparable measurements and a clear explanation of what changed.
FAQ
Why can coffee survey percentages add up to more than 100%?
Because the categories can overlap. Someone may drink coffee at home and elsewhere on the same day, or have both cold brew and espresso during a week. The NCA’s figures describe participation in categories, not mutually exclusive portions of a single total. Always check the question, population and reporting period before adding percentages.
Can we identify the fastest-growing coffee trend worldwide?
Not reliably from the evidence reviewed here. A global ranking would require comparable definitions, time periods and measures across markets. A manufacturer’s expanding product line, a national consumer survey and an increase in trade volume answer different questions. They can reveal useful directions without establishing one worldwide winner.
How often should an office review its coffee offer?
Review it when there is enough repeat-use evidence to distinguish a lasting preference from initial curiosity. As an editorial recommendation, use staff feedback alongside actual consumption and waste records, rather than changing equipment in response to a trend headline. Recheck supplier terms and relevant regulatory guidance when circumstances change.
Where to go next
Read Coffee Industry for the wider framework and The UK Coffee Industry for the national context behind coffee market trends. Specialty Coffee Roasters explains the provenance-focused part of the market, while Coffee Prices: The C-Market and Futures covers the mechanisms behind market movements.
Sources
- S1. UC Davis Library, The Third Wave of Coffee, exhibition material, 2025 to 2026. Historical characteristics of the movement. Source.
- S2. Specialty Coffee Association, What is Specialty Coffee, undated current page. Attribute-based definition of specialty coffee. Source.
- S3. National Coffee Association, Coffee Tops Beverage Charts Again, Specialty Coffee Hits New High, 15 September 2026. Survey methodology, specialty participation and cold-coffee comparisons. Source.
- S4. National Coffee Association, National Coffee Data Trends: Fall 2026 Media Highlights, 2026. Cold brew, nitro, RTD and consumption-location figures. Source.
- S5. National Coffee Association, 2026 NCDT Specialty Coffee Report, public report description and methodology, June 2026. Consumer-category definitions; the full commercial report was not accessed. Source.
- S6. CBI, Netherlands Ministry of Foreign Affairs, The United Kingdom’s Market Potential for Coffee, updated 26 August 2026. UK premiumisation and certification context. Source.
- S7. Starbucks, Nitro Cold Brew, undated current page. Manufacturer’s description of nitrogen infusion and drink texture. Source.
- S8. Nestlé, Third-quarter and Nine-month 2026 Sales, 22 October 2026. Company-reported cold-coffee development in its Asia, Oceania and Africa division. Source.
- S9. Competition and Markets Authority, Making Environmental Claims on Goods and Services, 2021. Substantiation, scope and clarity of environmental claims. Source.
- S10. Nab, C. and Maslin, M., UCL, Life Cycle Assessment Synthesis of the Carbon Footprint of Arabica Coffee: Case Study of Brazil and Vietnam Conventional and Sustainable Coffee Production and Export to the United Kingdom, 2020, Geo: Geography and Environment, 7(2), e00096. Peer-reviewed scenario modelling. Source.
- S11. Council of the European Union, EU Deforestation-free Products Regulation, reviewed 6 October 2026. Coffee coverage, traceability and application dates. Source.
- S12. DEFRA, Simpler Recycling: Workplace Recycling in England, updated 3 October 2025. Food waste, micro-firm exemption and compostable packaging. Source.
- S13. International Coffee Organization, Coffee Market Report: September 2026, 2026. Supply availability, certified stocks and weather uncertainty. Source.
Researched using publicly accessible survey releases, official guidance, company reporting and peer-reviewed research, with consumer measurements distinguished from company claims and editorial interpretation.
Last checked: November 2026